When most owners set up their business structure, the conversation is about tax. Sole trader or company? Is a trust worth the extra return? What’s the most efficient way to run this? It’s a fair question. It’s also only half the job.
One decision, two jobs
Your structure answers two questions at once. The compliance question: how is what the business earns
taxed, and what do you need to lodge? And the protection question: if something goes wrong (a large claim, a failed contract, a debt the business can’t pay), what’s exposed? Just the business, or your home, savings and land as well?
That’s why we say structure is where Protection and Compliance meet. In the four energies every business needs, Protection guards what growth has built, and Compliance keeps you eligible to compete. Structure is the one place where a single decision serves both.
Think of a boundary fence
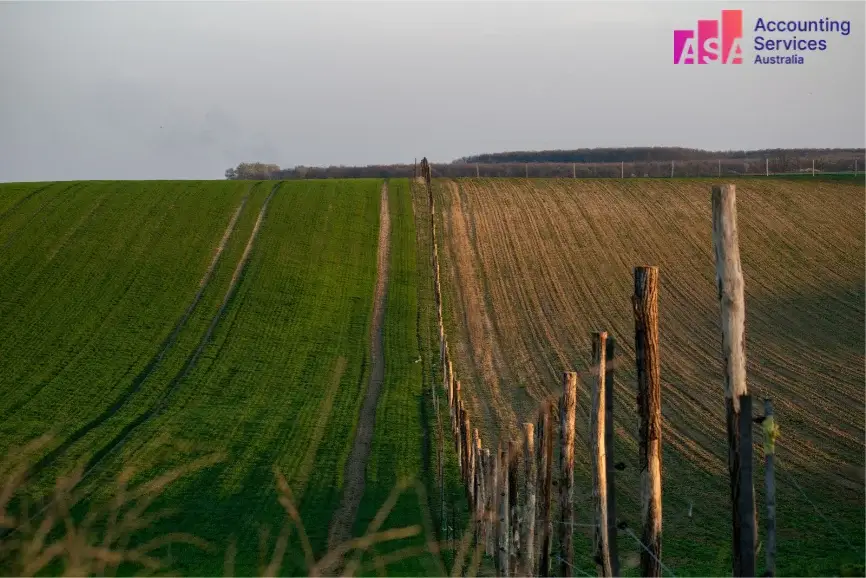
On a grazing property, the boundary fence marks where your land legally ends. It also keeps your stock in and trouble out. Nobody builds one fence for the titles office and another for the cattle. One fence does both jobs, and it’s in the wrong place; both jobs suffer.
Where it goes wrong
The problem is rarely that a structure was wrong on day one. It’s that it was chosen for the tax answer, at a time when there wasn’t much to protect. Take an earthmoving business on the Darling Downs (a composite example, not a real client). Twelve years ago the owner started as a sole trader: one machine, local jobs, simple and cheap.
Today the business turns over more than $1 million, employs three people and has two excavators on finance. The family home is in his name. On the tax side, most of the profit is now taxed at his top marginal rate. On the protection side, there’s no wall between the business and the house. If a job goes badly wrong, the home is in play. Same decision, two problems, and neither ever showed up as an error on a tax return.
Why this matters right now
If a discretionary trust is part of your structure, it sits squarely in this overlap The May 2026 Federal Budget proposed a 30% minimum tax on discretionary trusts from 1 July 2028, and the legislation was introduced to Parliament in October 2026. It is proposed, not yet law, and the details may still change. But it touches both sides at once: how the trust’s income is taxed, and whether the trust is still
the right way to hold what you’ve built. We’ll unpack it in plain English in November.
The question worth asking
Not “I paying too much tax?” but “is my structure still doing both jobs for the business I have now?”
If you’re not sure, our free Entity Structure Guide sets out how each of the five main structures answers both questions, in plain English.
General information only. This article does not take into account your personal financial situation, needs or objectives, and is not tax, legal, financial or investment advice. The Budget measures referred to are proposals and are not yet law, and they may change. Please speak with us before acting. Liability limited by a scheme approved under Professional Standards Legislation.
Justin Maddock
Justin Maddock is a Chartered Accountant and CPA with more than 20 years’ experience in public practice.
Accounting Services Australia